Small Business Loans US 2026: Government Programs up to $100K
Anúncios
Small businesses in the US can secure up to $100,000 through new government programs and enhanced funding options available in 2026.
Anúncios
Are you a small business owner in the United States looking to fuel your growth or kickstart a new venture? In 2026, the landscape for securing small business loans in the US for 2026: securing up to $100,000 with new government programs is more promising than ever, with expanded opportunities and streamlined processes designed to empower entrepreneurs across the nation.
Anúncios
Understanding the 2026 Small Business Funding Landscape
The year 2026 marks a significant shift in how small businesses in the US can access capital. With an increased focus on economic resilience and supporting local economies, new government programs and enhancements to existing initiatives are making it easier for entrepreneurs to secure the funding they need, particularly for amounts up to $100,000. This section will delve into the overarching changes and what they mean for your business.
Government’s Renewed Commitment to Small Businesses
The federal government, recognizing the critical role small businesses play in job creation and innovation, has intensified its commitment. This includes not only direct funding initiatives but also efforts to simplify application processes and increase awareness of available resources. The goal is to reduce barriers to entry for capital, especially for underserved communities and emerging industries.
- Increased Program Budgets: Several key government loan programs have seen budget increases, allowing more businesses to receive funding.
- Streamlined Application Portals: New digital platforms are being rolled out to make applying for government-backed loans faster and more intuitive.
- Enhanced Educational Resources: The Small Business Administration (SBA) and its partners are offering more workshops and online guides to help businesses navigate the funding process.
Economic Outlook and Loan Accessibility
The economic forecast for 2026 suggests a stable environment, which is generally favorable for lending. Lenders, buoyed by government guarantees and a clearer economic picture, may be more willing to extend credit to qualified small businesses. This improved accessibility is particularly beneficial for those seeking smaller loan amounts, which are often crucial for day-to-day operations or modest expansion plans.
The shift towards smaller loan amounts up to $100,000 reflects a strategic focus on supporting a broader base of businesses, from startups to established enterprises looking for working capital or minor equipment upgrades. This targeted approach ensures that funding reaches a wider array of businesses that might not qualify for larger, more complex commercial loans.
In conclusion, the 2026 funding landscape for small businesses is characterized by robust government support and a positive economic outlook. These factors combine to create an environment where securing capital, especially for amounts up to $100,000, is more attainable for a diverse range of entrepreneurs.
Key Government Loan Programs for 2026
For small businesses in 2026, understanding the specific government programs available is crucial. These programs are designed with varying eligibility criteria and purposes, but all aim to provide accessible funding. This section outlines the primary government-backed loan options you should consider when seeking up to $100,000.
SBA 7(a) Loan Program Enhancements
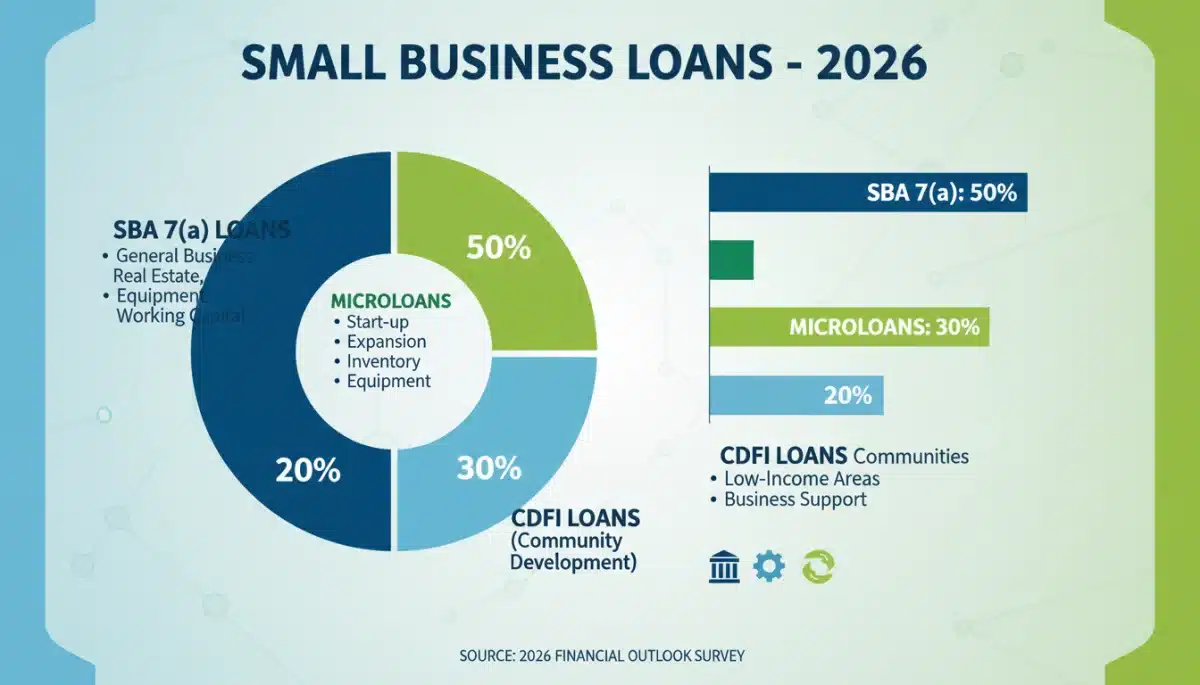
The SBA 7(a) loan program remains a cornerstone of small business financing. For 2026, there are notable enhancements, especially for smaller loan amounts. The SBA guarantees a portion of these loans, reducing risk for lenders and making it easier for small businesses to qualify. For loans under $100,000, the application process has been further simplified, often requiring less extensive documentation.
- Simplified Application for Micro-Loans: A dedicated track for 7(a) loans under $50,000 has been introduced, accelerating approval times.
- Increased Lender Participation: More banks and credit unions are participating in the 7(a) program due to favorable government guarantees.
- Flexible Use of Funds: Funds can be used for various purposes, including working capital, equipment purchases, and even real estate acquisition.
SBA Microloan Program Expansion
The SBA Microloan Program is specifically tailored for very small businesses and certain non-profit childcare centers, offering loans up to $50,000. In 2026, this program has seen an expansion in its reach and capacity, with more intermediary lenders empowered to disburse funds. These intermediaries often provide business counseling alongside the loan, a valuable resource for new or growing businesses.
The Microloan program is particularly attractive for startups and businesses in underserved communities that may struggle to secure traditional bank financing. The lower loan amounts mean less stringent collateral requirements and a focus on the business plan and character of the borrower.
Community Development Financial Institutions (CDFIs)
CDFIs are private financial institutions dedicated to delivering responsible, affordable financial products and services to help low-income, low-wealth, and other disadvantaged people and communities. In 2026, government funding for CDFIs has increased significantly, allowing them to provide more small business loans, often with more flexible terms than conventional lenders. They are an excellent option for businesses seeking loans up to $100,000, particularly those in economically distressed areas.
These institutions often prioritize community impact alongside financial viability, making them a supportive partner for businesses aiming to create jobs and stimulate local growth. Their expertise in local markets also provides an added advantage for applicants.
In summary, the SBA 7(a) program, SBA Microloans, and CDFIs represent the core government-backed avenues for small businesses seeking up to $100,000 in 2026. Each offers unique benefits and caters to different business needs, making it essential to explore all options.
Eligibility and Application Process for 2026
Navigating the eligibility requirements and application process for government-backed small business loans can seem daunting, but with the 2026 updates, it’s becoming more straightforward. This section breaks down what businesses need to qualify and how to effectively apply for funding up to $100,000.
General Eligibility Criteria
While specific requirements vary slightly by program and lender, several common criteria apply to most government-backed small business loans. Understanding these foundational elements is the first step toward a successful application. Typically, businesses must operate for profit, be physically located and operate in the US, and have invested some of their own equity.
- Business Type: Must be a for-profit entity (sole proprietorship, partnership, corporation, LLC).
- Location: Primarily operate within the United States.
- Size Standards: Meet the SBA’s definition of a small business (based on revenue or number of employees, varying by industry).
- Creditworthiness: Demonstrate a reasonable credit history, though some programs offer more flexibility for newer businesses.
- Need for Funds: Show a sound business purpose for the loan.
Required Documentation
Preparing the right documentation is paramount for a smooth application. For loans up to $100,000, the documentation requirements have been somewhat simplified to expedite the process. However, having a comprehensive set of financial and business documents ready is always advisable.
Common documents include a detailed business plan, personal and business financial statements, tax returns, and legal documents related to your business structure. For smaller loans, lenders might place more emphasis on recent bank statements and a clear projection of how the funds will be used and repaid.
Streamlined Application Steps
The application process in 2026 benefits from technological advancements and policy changes aimed at efficiency. Many lenders now offer online portals, and the SBA itself has improved its resources for guiding applicants. The general steps involve identifying the right program, preparing your documents, finding an approved lender, submitting your application, and then undergoing the underwriting process.
For loans under $100,000, some lenders offer expedited review processes, which can significantly reduce the time from application to funding. It is always recommended to consult with an SBA resource partner, such as a Small Business Development Center (SBDC) or SCORE mentor, to ensure your application is as strong as possible.
To conclude, understanding eligibility and meticulously preparing for the application process are critical. The 2026 landscape offers simplified paths for small business loans up to $100,000, but diligence in meeting requirements and documentation remains key to success.
Maximizing Your Chances for Approval
Securing a small business loan, even with enhanced government programs, requires strategic preparation. For amounts up to $100,000, lenders are looking for clear indicators of a business’s viability and the borrower’s reliability. This section provides actionable advice to help you maximize your approval chances in 2026.
Crafting a Compelling Business Plan
A well-structured and realistic business plan is your roadmap and your pitch to lenders. It demonstrates your understanding of the market, your operational strategy, and your financial projections. Even for smaller loan amounts, a clear plan instills confidence in lenders that you have a solid vision and a path to repayment.
- Executive Summary: A concise overview of your business, its mission, and what you aim to achieve with the loan.
- Market Analysis: Demonstrate a deep understanding of your target market, competition, and unique selling propositions.
- Financial Projections: Provide realistic and conservative financial forecasts, including cash flow statements and profit and loss projections.
- Management Team: Highlight the experience and expertise of your leadership team.
Improving Your Credit Profile
Both personal and business credit scores play a significant role in loan approval. For 2026, while some government programs offer flexibility, a strong credit profile will always be an advantage. Take steps to review your credit reports for inaccuracies and work on improving your scores before applying.
Ensure all existing debts are managed responsibly, and try to reduce outstanding balances where possible. A healthier credit score signals to lenders that you are a reliable borrower, potentially leading to better loan terms and a higher chance of approval for small business loans in the US for 2026.
Building Relationships with Lenders
Don’t wait until you need a loan to start interacting with financial institutions. Building relationships with local banks, credit unions, and CDFIs can be incredibly beneficial. Attend their small business workshops, open a business account, and discuss your future funding needs. A pre-existing relationship can make the application process smoother and increase your chances of securing favorable terms.
Lenders are more likely to approve loans for businesses they know and trust. By demonstrating your commitment and transparency early on, you position yourself as a reliable and informed borrower. This proactive approach can significantly enhance your prospects for securing up to $100,000 in funding.
In essence, maximizing your loan approval chances involves a combination of thorough planning, financial diligence, and proactive engagement with potential lenders. These efforts will pay dividends when seeking small business loans in 2026.
New Government Initiatives and Their Impact
The year 2026 brings with it several new government initiatives specifically designed to bolster small business growth and access to capital. These programs are not merely expansions of old ones but represent innovative approaches to address modern economic challenges. Understanding these new initiatives can provide a competitive edge for businesses seeking up to $100,000.
Targeted Funding for Emerging Industries
Recognizing the importance of innovation, the government has introduced specialized funding streams for businesses in emerging sectors such as green technology, AI, and biotechnology. These initiatives aim to accelerate growth in areas critical for future economic competitiveness. Small businesses in these fields may find tailored loan programs with more favorable terms and specialized guidance.
- Green Business Boost: Loans specifically for businesses focused on sustainable practices and renewable energy.
- Tech Startup Grants: While not strictly loans, new grant programs can complement loan applications for high-potential tech startups.
- Rural Innovation Fund: Support for businesses bringing new technologies and services to rural communities.
Enhanced Support for Veteran and Women-Owned Businesses
The government continues its commitment to supporting historically underserved groups. For 2026, there are enhanced programs and resources specifically for veteran and women-owned businesses. These initiatives include not only access to capital but also mentorship, training, and networking opportunities. Such support is crucial for fostering diversity and inclusion in the entrepreneurial ecosystem.
These programs often feature reduced interest rates, lower collateral requirements, and dedicated counselors who understand the unique challenges faced by these business owners. This tailored assistance significantly improves the likelihood of securing small business loans up to $100,000.
Digital Transformation and Access
A significant new initiative focuses on digital transformation. The government is investing in programs that help small businesses adopt new technologies, improve their online presence, and enhance cybersecurity. Loans under this initiative can be used to purchase software, hardware, or services that contribute to digital modernization, making businesses more resilient and competitive.
This focus on digital readiness is vital in today’s economy. Businesses that can demonstrate a clear plan for digital adoption and growth will be well-positioned to benefit from these new funding opportunities. This strategic investment ensures that American small businesses remain at the forefront of technological advancement.
In conclusion, the new government initiatives for 2026 are diverse and impactful, targeting specific industries and demographic groups while also promoting digital readiness. These programs offer valuable avenues for small businesses to secure up to $100,000 and thrive in a dynamic economic landscape.
Beyond Government Loans: Alternative Funding Options for 2026
While government programs are a fantastic resource for small business loans in 2026, they are not the only option. A comprehensive funding strategy often involves exploring a mix of traditional and alternative financing sources. This section examines other viable avenues for securing up to $100,000 in capital.
Traditional Bank Loans and Lines of Credit
Despite the rise of alternative lenders, traditional banks and credit unions remain a primary source of funding. For amounts up to $100,000, many banks offer conventional term loans or lines of credit. These typically require a strong credit history, established business operations, and collateral. The advantage often lies in lower interest rates and longer repayment terms compared to some alternative options.
Building a strong banking relationship can open doors to various financial products beyond just loans, including cash management services and business advisory. It’s worth exploring what your current bank offers, as they may have special programs for existing customers.
Online Lenders and Fintech Platforms
The digital lending landscape continues to evolve rapidly. Online lenders and fintech platforms offer quick and convenient access to capital, often with less stringent requirements than traditional banks. For small business loans up to $100,000, these platforms can provide term loans, short-term loans, or merchant cash advances. The application process is typically fully online and approval can be much faster.
However, it’s crucial to compare interest rates and fees carefully, as these can sometimes be higher than government-backed or traditional bank loans. Researching reputable platforms and reading reviews is essential to ensure you’re getting a fair deal.
Crowdfunding and Angel Investors
For businesses with innovative ideas or strong community appeal, crowdfunding platforms can be an excellent way to raise capital without incurring debt. Equity crowdfunding allows individuals to invest in your business in exchange for a stake, while reward-based crowdfunding offers products or services in return for contributions. Angel investors, wealthy individuals who provide capital for a startup or small business, often in exchange for ownership equity, are another option for higher-risk, high-reward ventures.
These options require a compelling story and a well-executed marketing campaign to attract investors. While they don’t involve traditional loan repayments, they do come with their own set of considerations, such as giving up equity or fulfilling rewards.
In conclusion, a diverse approach to funding is often the most effective. While government programs are invaluable, exploring traditional bank options, online lenders, and even crowdfunding can provide additional pathways to secure the $100,000 your small business needs in 2026.
Strategic Planning for Loan Repayment
Securing a small business loan is only half the battle; successfully managing its repayment is equally critical for your business’s financial health and future borrowing capacity. Strategic planning for loan repayment in 2026 involves more than just making timely payments; it requires careful budgeting, cash flow management, and contingency planning.
Developing a Robust Repayment Strategy
Before you even receive the funds, you should have a clear plan for how you will repay the loan. This involves detailed financial forecasting that accounts for your new debt obligations. Understand the interest rate, repayment schedule (monthly, weekly, etc.), and any potential fees. Integrate these costs directly into your operational budget.
- Cash Flow Projections: Create detailed monthly cash flow forecasts to ensure you have sufficient funds to cover loan payments.
- Budget Allocation: Clearly allocate a portion of your revenue specifically for loan repayment.
- Cost-Benefit Analysis: Regularly assess how the loan is impacting your business’s profitability and adjust strategies as needed.
Monitoring Business Performance
Continuous monitoring of your business’s financial performance is essential. Keep a close eye on key metrics such as revenue growth, profit margins, and operational expenses. If your business is underperforming, it’s crucial to identify the issues early and implement corrective actions. This proactive approach can prevent repayment difficulties before they arise.
Utilize accounting software and financial dashboards to track your progress against your projections. This data will not only help you stay on track with your loan but also provide valuable insights into the overall health of your business operations. Timely adjustments can make a significant difference.
Contingency Planning and Communication
Even the best-laid plans can encounter unexpected challenges. Develop a contingency plan that outlines how your business would manage loan repayments during leaner periods. This might include identifying potential cost-cutting measures, securing a line of credit for emergencies, or having a reserve fund. Open communication with your lender is also vital.
If you anticipate difficulties in making a payment, contact your lender immediately. Many lenders are willing to work with businesses facing temporary setbacks, potentially offering deferrals or restructured payment plans. Hiding from the problem will only exacerbate it. Proactive communication demonstrates responsibility and can preserve your relationship with the lender for future needs.
Ultimately, strategic planning for loan repayment is a continuous process that ensures the long-term sustainability of your business. By focusing on robust budgeting, performance monitoring, and proactive communication, you can successfully manage your small business loans in the US for 2026 and build a strong financial foundation.
| Key Point | Brief Description |
|---|---|
| 2026 Government Programs | New and enhanced initiatives making small business loans up to $100,000 more accessible. |
| SBA Loan Options | SBA 7(a) and Microloan programs offer simplified applications and broader reach. |
| Eligibility & Preparation | Focus on strong business plans, credit profiles, and complete documentation for approval. |
| Repayment Strategy | Crucial for long-term financial health, involving budgeting, monitoring, and communication. |
Frequently Asked Questions About Small Business Loans in 2026
The main government programs for small business loans in 2026 include the SBA 7(a) loan program, the SBA Microloan program, and loans facilitated through Community Development Financial Institutions (CDFIs). These programs offer various benefits and terms, often with government guarantees to encourage lending to small businesses.
Yes, many government-backed programs, particularly the SBA 7(a) and some CDFI offerings, are structured to provide loans up to and including $100,000. These specific amounts often fall into categories with streamlined application processes designed for smaller funding needs.
Key eligibility requirements generally include operating as a for-profit business in the US, meeting SBA size standards, having a reasonable credit history, and demonstrating a clear purpose for the funds. Specific criteria may vary by program and the individual lender’s policies.
To improve your approval chances, focus on developing a strong business plan, maintaining a healthy personal and business credit score, and gathering all necessary financial documentation. Building relationships with potential lenders and seeking advice from SBA resource partners can also be highly beneficial.
Yes, 2026 sees new government initiatives targeting emerging industries like green technology and AI. There’s also enhanced support and specialized programs for veteran and women-owned businesses, offering tailored resources and potentially more favorable loan terms to these specific groups.
Conclusion
The landscape for small business loans in the US for 2026: securing up to $100,000 with new government programs presents a wealth of opportunities for entrepreneurs. With renewed government commitment, expanded program budgets, and simplified application processes, accessing crucial capital is more achievable than ever. By understanding the available programs, meticulously preparing your application, and strategically planning for repayment, small business owners can leverage these resources to foster growth, innovation, and economic stability. The future for American small businesses looks bright, supported by a robust framework designed to empower their success.